The Clothing Industry and the Single European Market
A Textiles Intelligence research report on the EC clothing industry as the single European market was completed
The EC clothing industry employs a million people and ranks among the leading ten industries in the European Community. Its output, at about US$60 billion a year, is almost double that of the USA and Japan. But while it remains a major industry it has had to face a number of difficulties. This Textiles Intelligence report looks at the factors affecting the clothing industry in the EC and examines its future prospects, with particular attention to what the completion of the single European market would mean for the industry's structure. Textiles Intelligence, formed in 1992 as a spin-off from the Economist Intelligence Unit, provides global business information to the international fibre, textile and apparel industry and publishes over 30 in-depth research reports alongside its Textile Outlook International and Technical Textile Markets periodicals.
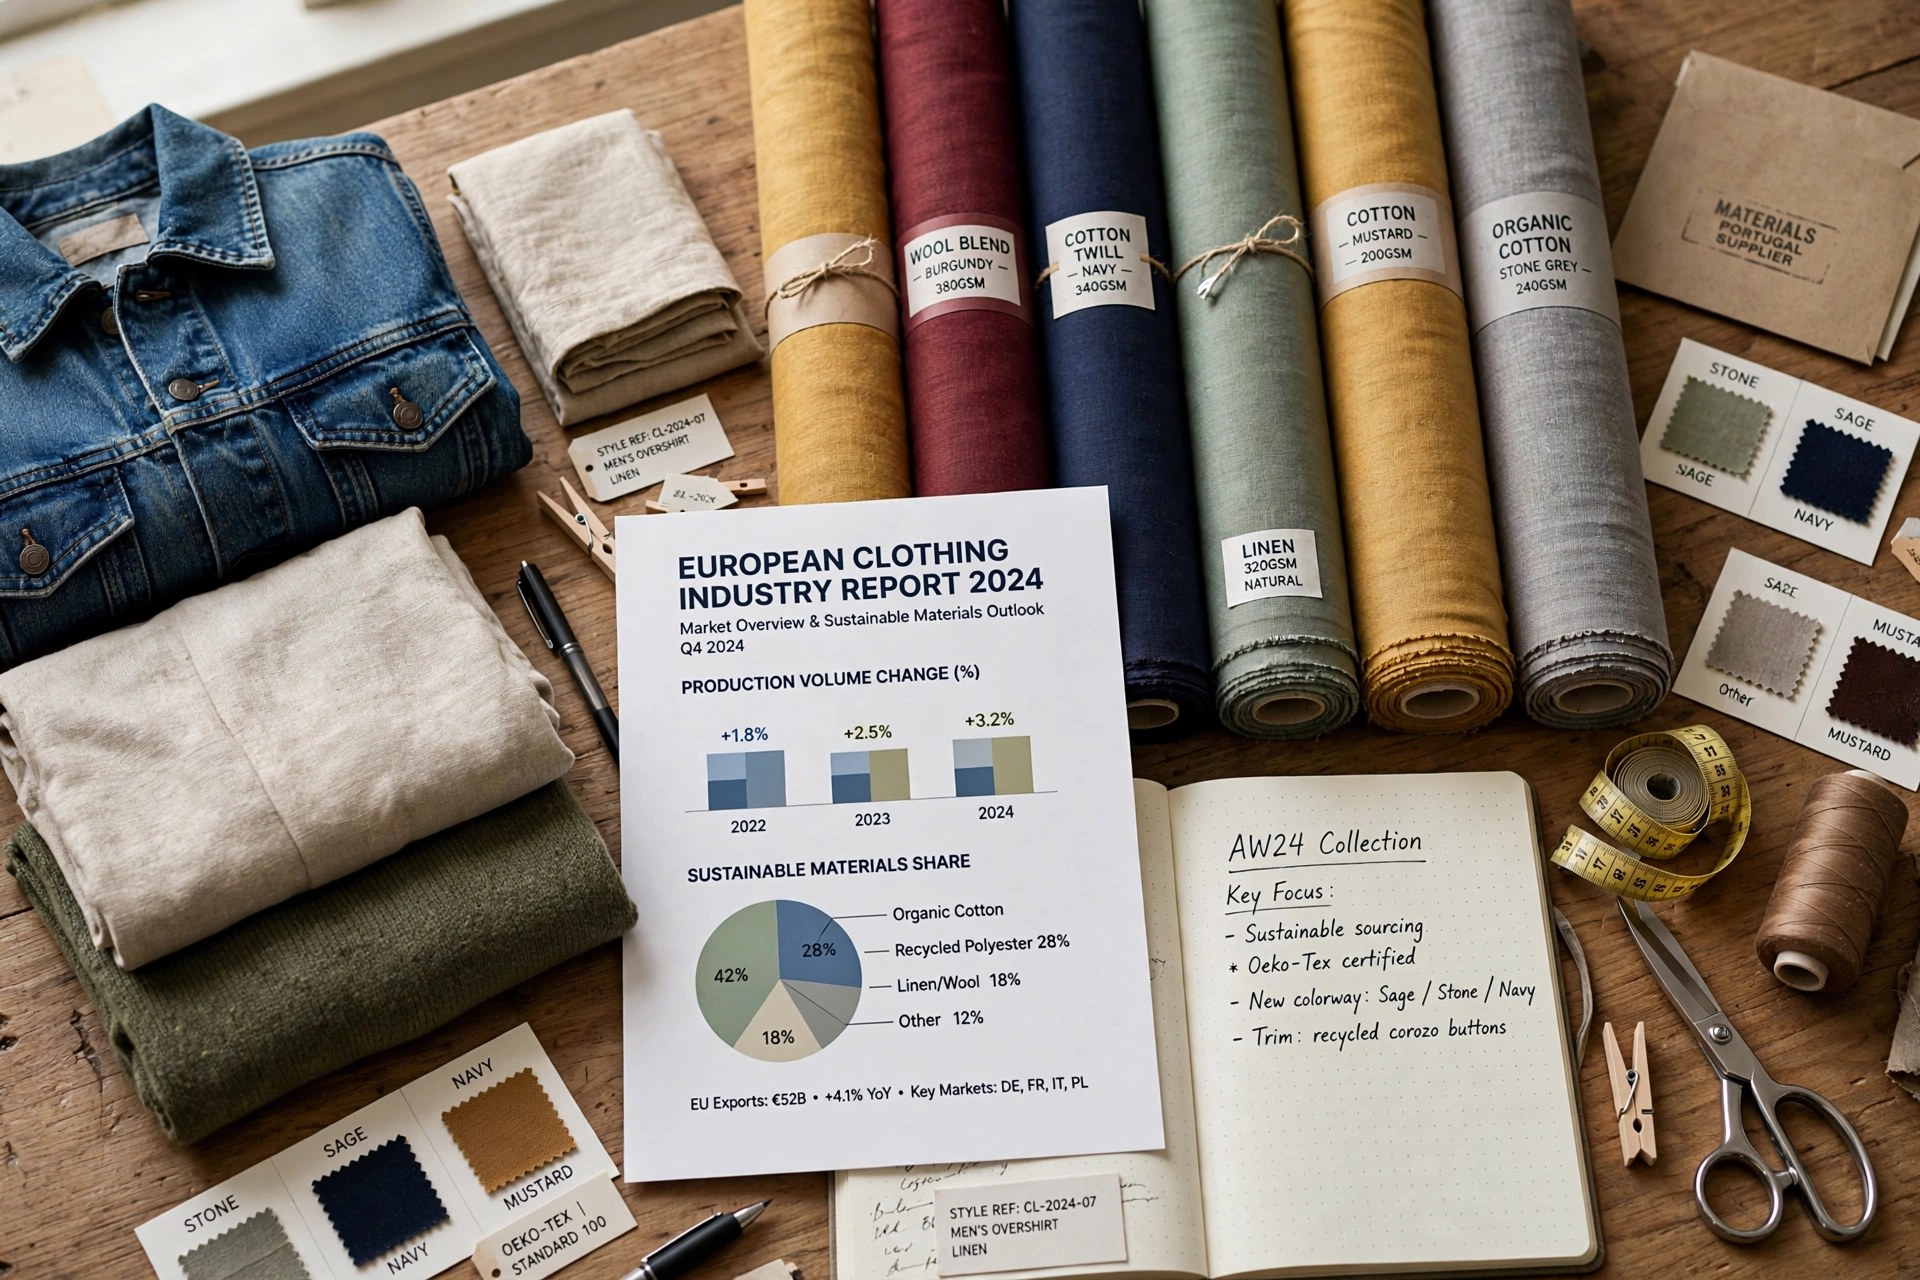
A Million-Job Industry Facing Change
Scale is the report's starting point. A million employees and annual output of about US$60 billion — almost double the output of the USA and Japan — made clothing one of the European Community's leading ten industries, and one no member state could treat as marginal. Yet the industry faced real difficulties: import competition, technological change in production, and the restructuring already under way in firm strategies during the 1980s. The report's first chapter sets out the industry's structure and characteristics, its importance in EC and member state economies, its factors of production and technological change, and its performance.
The Market, Trade and Restructuring
Chapter 2 measures the EC clothing market — its size in the Community and in member states, and the determinants of demand. Chapter 3 places the industry in its international environment: export specialisation by member state, intra-EC and extra-EC trade, EC and international competitiveness, and EC trade policy. Chapter 4 examines current developments and industrial restructuring — the heritage of a restructured industry, the strategies of EC clothing firms in the 1980s, and future developments — before Chapter 5 addresses the completion of the single European market directly: its internal impact, its external impact, its effect on industry structures, and the EC Brite Programme.
The country chapters then work through restructuring state by state: France, Italy, West Germany and the UK in Chapter 6; Spain, Portugal and Greece in Chapter 7; and Belgium, the Netherlands, Denmark and the Republic of Ireland in Chapter 8. A concluding chapter draws together the forces for change and future prospects, including the challenge of automation, and the report closes with a bibliography and sources of information.
Who This Report Serves
Clothing companies planning for the single market needed exactly this sequence: the size of the prize, the trade position, and then the competitive reality country by country. A manufacturer in one member state could read its own restructuring chapter against the chapters for its neighbours and competitors, and judge how the single market's internal and external effects would redistribute production inside the Community. Trade associations, regional development bodies and suppliers to the clothing industry form the report's second readership, using its market size and industry structure data for the EC as a whole and for each member state economy.
Common Questions
How large was the EC clothing industry in this report?
It employed a million people, ranked among the leading ten industries in the European Community, and produced output of about US$60 billion a year — almost double that of the USA and Japan.
Which countries get their own restructuring chapters?
France, Italy, West Germany and the UK; Spain, Portugal and Greece; and Belgium, the Netherlands, Denmark and the Republic of Ireland — preceded by chapters on the EC market, international trade and the completion of the single European market.
What single market questions does the report address?
The internal impact and external impact of completing the single European market, its effect on industry structures, the EC Brite Programme, and the industry's future prospects including the challenge of automation.